Top 5 Business Bank Accounts for Freelancers in 2027 (Mostly Free & Easy to Open)
Here is a fundamental question for every independent worker: when a client pays you, where does that money land? If the answer is your personal checking account, you are making tax time, expense tracking, and long-term budgeting significantly harder than they need to be. According to economic data from MBO Partners, a record 74.9 million Americans earn independent income. In IRS Publication 583 ("Starting a Business and Keeping Records"), the tax authority strongly advises opening a dedicated business checking account to clearly segregate personal and commercial transactions. Today, modern financial technology has eliminated monthly maintenance fees, minimum balance requirements, and tedious paperwork. In this authoritative 2027 guide, we rank the top 5 business bank accounts designed specifically for freelancers, evaluating fees, tax automation tools, checking interest rates, and underlying FDIC deposit safety.

Try our free Freelance Hourly Rate Calculator to calculate your target hourly rate.
1. Why Bother? The IRS Rule & The Cost of Commingling Funds
While sole proprietors in the United States are not legally mandated to open a dedicated commercial bank account, continuing to operate out of a personal checking account is one of the costliest operational mistakes a freelancer can make. Mixing personal expenses (groceries, rent, entertainment) with client invoices creates messy records that make identifying legitimate deductible business expenses—such as software subscriptions, home office equipment, and travel—an excruciating tax-season nightmare.
Opening a dedicated business account delivers three immediate, game-changing advantages:
• Bulletproof Audit Defense: When business income and expenses flow through a single dedicated statement, verifying Schedule C deductions to the IRS or an accountant takes minutes rather than days.
• Professional Client Invoicing: Clients receive invoices and payment instructions made out to your trade or professional business name rather than an individual person, establishing immediate credibility.
• Crystal-Clear Profit Clarity: You instantly know whether your freelance business is truly profitable after business expenses and taxes, preventing you from accidentally spending money that belongs to Uncle Sam.
#5: Relay — The Ultimate Envelope Budgeting & Profit First Platform
• Pricing: $0 / month (Relay Starter plan with zero account maintenance fees and no minimum deposit)
• Checking APY Interest: 1.19% APY (Variable yield on cash balances)
• Banking Partner & FDIC Protection: Deposits held by Thread Bank (Member FDIC), with an automated sweep network extending FDIC insurance up to $3,000,000.
• Standout Superpower: Up to 20 individual checking accounts and 50 physical or virtual debit cards with automated percentage cash-splitting rules.
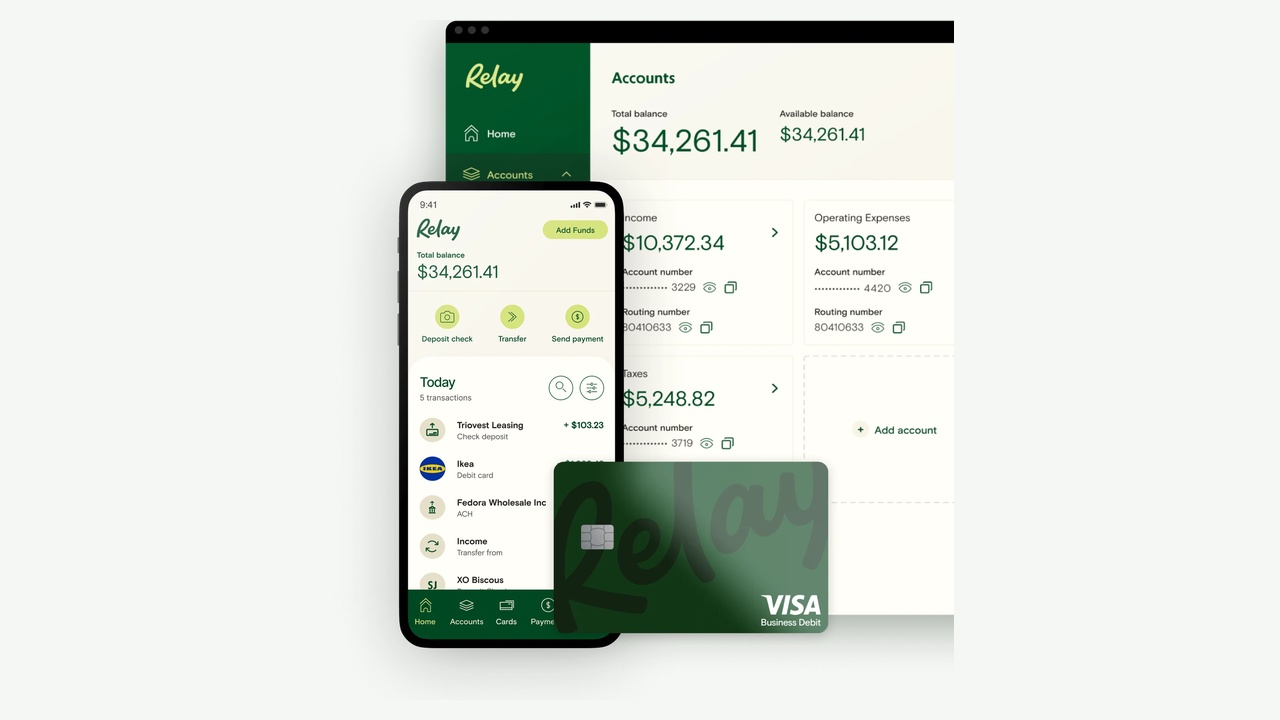
Coming in at #5 is Relay, an account engineered specifically around visual budgeting and the renowned "Profit First" cash management methodology. While most traditional banks limit you to a single checking account and penalize you for opening multiple accounts, Relay’s free Starter plan allows you to open up to 20 separate checking accounts with unique account and routing numbers under one login.
This envelope architecture allows freelancers to create automatic cash-allocation rules. Every time a $3,000 client invoice clears, Relay can automatically allocate 30% into your "Taxes" account, 50% into "Owner Pay," 15% into "Operating Expenses," and 5% into "Profit." You never have to calculate your tax or payroll splits manually. Furthermore, Relay offers zero-fee ACH transfers, domestic wires for just $5, and seamless bidirectional integrations with QuickBooks Online and Xero.
• Who It Is Best For: Solopreneurs and freelancers who love visual budgeting buckets, follow the Profit First methodology, and want separate sub-accounts to segregate taxes, emergency reserves, and operating capital.
#4: Bluevine — High-Yield Business Checking for Idle Cash Cushions
• Pricing: $0 / month (Standard plan with no monthly fees, no minimum balance requirements, and free incoming wires)
• Checking APY Interest: 1.30% APY on balances up to $250,000 (qualifying conditions apply); upgradable to 1.75% ($30/mo Plus) or 3.00% ($95/mo Premier)
• Banking Partner & FDIC Protection: Deposits held by Coastal Community Bank (Member FDIC), with sweep networks providing up to $3,000,000 in FDIC coverage.
• Standout Superpower: Industry-leading interest yields earned directly within checking, paired with physical cash deposits at over 90,000 retail locations nationwide.
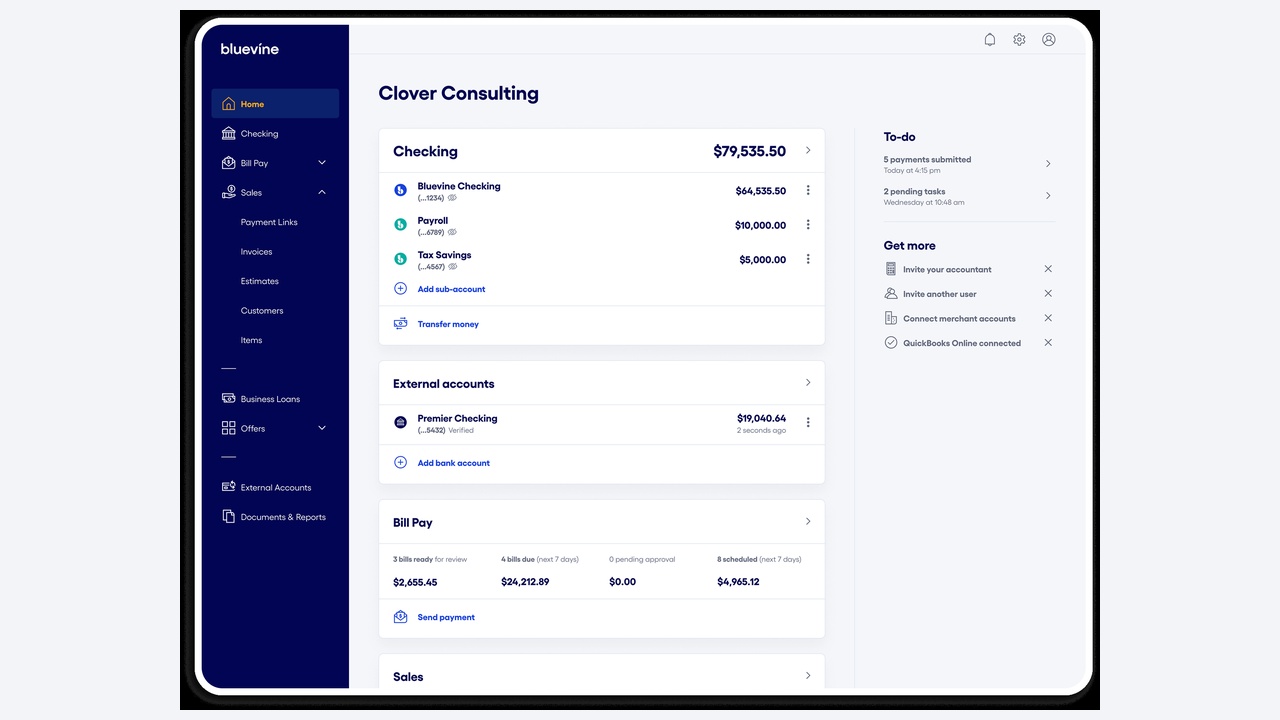
Ranking at #4 is Bluevine, an established digital banking leader whose core pitch to freelancers is straightforward: why should your operating cash sit idle earning 0.00% when it could be compounding every single month? Most commercial business accounts pay zero interest or force you to lock capital into restrictive savings accounts or certificates of deposit.
Under Bluevine’s free Standard plan, you earn an impressive 1.30% APY on checking balances up to $250,000 by meeting one of two simple monthly activity thresholds: spending $500 per month with your Bluevine debit card or receiving at least $2,500 per month in customer payments. For freelancers who occasionally handle physical cash (such as event photographers, videographers, or consultants), Bluevine partners with the Green Dot network, allowing cash deposits at more than 90,000 retail stores (including Walgreens, Walmart, and 7-Eleven) for a modest retail fee.
• Who It Is Best For: Freelancers who maintain a substantial cash cushion ($5,000 to $100,000+) in their operating account and want high interest compounding directly on their checking balance without manual transfers.
⚡ Mid-Point Reality Check: What Should Your True Hourly Rate & Tax Reserve Be?
Setting up a fee-free business account is only half the battle. The other half is ensuring your client billing rates are high enough to cover self-employment tax (15.3% for FICA/Medicare), health insurance, retirement contributions, and unpaid administrative downtime.
Before sending your next client proposal, stress-test your numbers with Percentio’s free specialized calculation tools:
• Freelance Hourly Rate Calculator — Calculate your exact target billable rate based on your desired take-home salary, annual overhead costs, and realistic billable client hours.
• Tax Calculator — Estimate your federal and state tax burdens to know exactly what percentage to route into your tax withholding account.
• Savings Calculator — Model your monthly savings timeline to build a bulletproof 3-to-6-month business emergency cushion.
#3: Mercury — High-Growth Tech Banking with Zero Wire Fees
• Pricing: $0 / month (Zero monthly maintenance fees, zero account minimums, and zero hidden transaction penalties)
• Checking APY Interest: Cash earns Treasury-backed yields via Mercury Treasury on larger balances ($250,000+)
• Banking Partner & FDIC Protection: Deposits held by Choice Financial Group and Column N.A. (Members FDIC), utilizing sweep networks extending FDIC insurance up to $5,000,000. In 2026, Mercury received preliminary approval for its own national bank charter.
• Standout Superpower: 100% free domestic wires and free international wires sent in U.S. dollars, accompanied by developer-grade APIs and software-like UX.
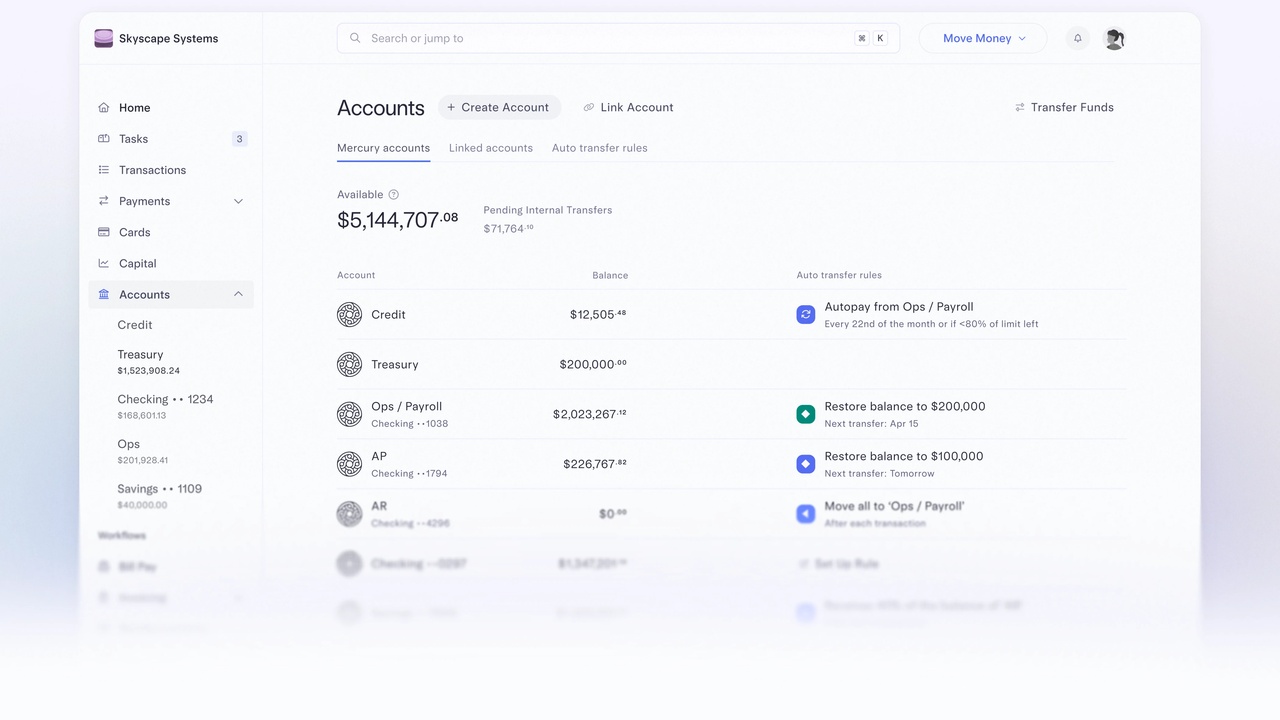
Taking the bronze medal at #3 is Mercury, widely recognized as the premier banking platform for technology startups, digital agencies, and high-earning online consultants. While traditional banks charge $25 to $35 for every single outbound wire transfer, Mercury makes domestic wires and international wires in USD completely free.
Mercury’s web and mobile interfaces feel like modern software rather than a clunky legacy bank portal. Freelancers get unlimited virtual debit cards with custom spend limits (ideal for segregating recurring SaaS subscriptions like Adobe, Figma, and Webflow), automated receipt matching via email forwarding, and read-only accountant access. With up to $5 million in sweep-network FDIC insurance, Mercury easily accommodates solo operators planning to scale into multi-person boutique agencies.
• Who It Is Best For: Digital nomads, software developers, creative agency owners, and high-income freelancers who frequently send or receive wire transfers and want an ultra-clean, modern banking experience.
#2: Wise Business — The Multi-Currency Gold Standard for International Clients
• Pricing: $0 / month ($31 one-time registration fee in the U.S. or £50 in the UK; zero monthly subscription fees)
• Currency Scope: Hold and manage over 40 global currencies; receive payments like a local with dedicated account details in 22 currencies (including USD, EUR, GBP, CAD, AUD, and JPY).
• Conversion Economics: Transparent mid-market exchange rates with conversion fees starting from just 0.23% (compared to 3.0%–5.0% bank markups).
• Regulatory Protection: Regulated as a licensed Money Services Business (MSB) and payment institution worldwide, safeguarding customer balances in segregated tier-1 commercial institutions.
Securing the silver medal at #2 is Wise Business, the undisputed global champion for freelancers whose client roster spans multiple countries. If you work with clients in the United Kingdom, Europe, Canada, or Australia, having clients wire funds to a traditional U.S. bank account is extraordinarily expensive: your client pays an international wire fee, intermediary banks take unexpected processing cuts, and your bank slaps a punishing 3% to 5% hidden markup onto the foreign exchange conversion rate.
Wise Business completely eliminates this friction by giving you local domestic account details in 22 major currencies. A client in London pays your UK sort code in British Pounds via local Faster Payments; a client in Berlin pays your European IBAN in Euros via SEPA. The money lands instantly with zero incoming fees. You can hold those funds in your Wise multi-currency wallet, spend them globally with your Wise business debit card, or convert them back to your local currency at the true mid-market exchange rate.
• Who It Is Best For: Freelancers, remote contractors, and digital nomads working with cross-border clients abroad who refuse to lose 3% to 5% of their hard-earned revenue to predatory international banking fees.
#1: Found — The #1 All-in-One Tax-Automating Bank Account for Solopreneurs
• Pricing: $0 / month (Core plan is 100% free with no monthly fees, no minimum balances, and free invoicing); optional Found Plus at $35 / month adds 1.50% APY on up to $20,000 and advanced bookkeeping.
• Banking Partner & FDIC Protection: Deposits held by Lead Bank (Member FDIC), providing standard $250,000 FDIC coverage.
• Standout Superpower: Automated real-time tax withholding, live Schedule C expense categorization, receipt capture, and automated 1099-NEC contractor filing.
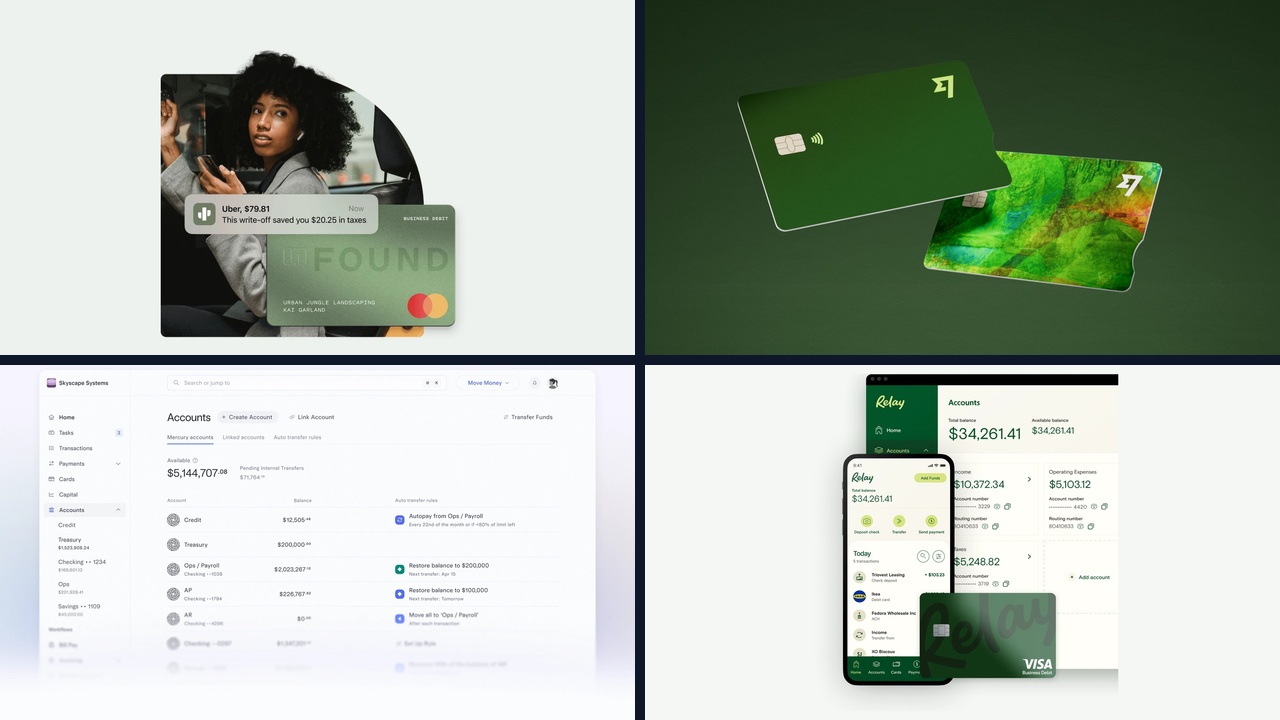
Standing unrivaled at the absolute summit of our rankings at #1 is Found. While every other business account functions simply as a digital ledger to store money, Found was designed from the ground up to solve the single problem that independent workers dread most: taxes.
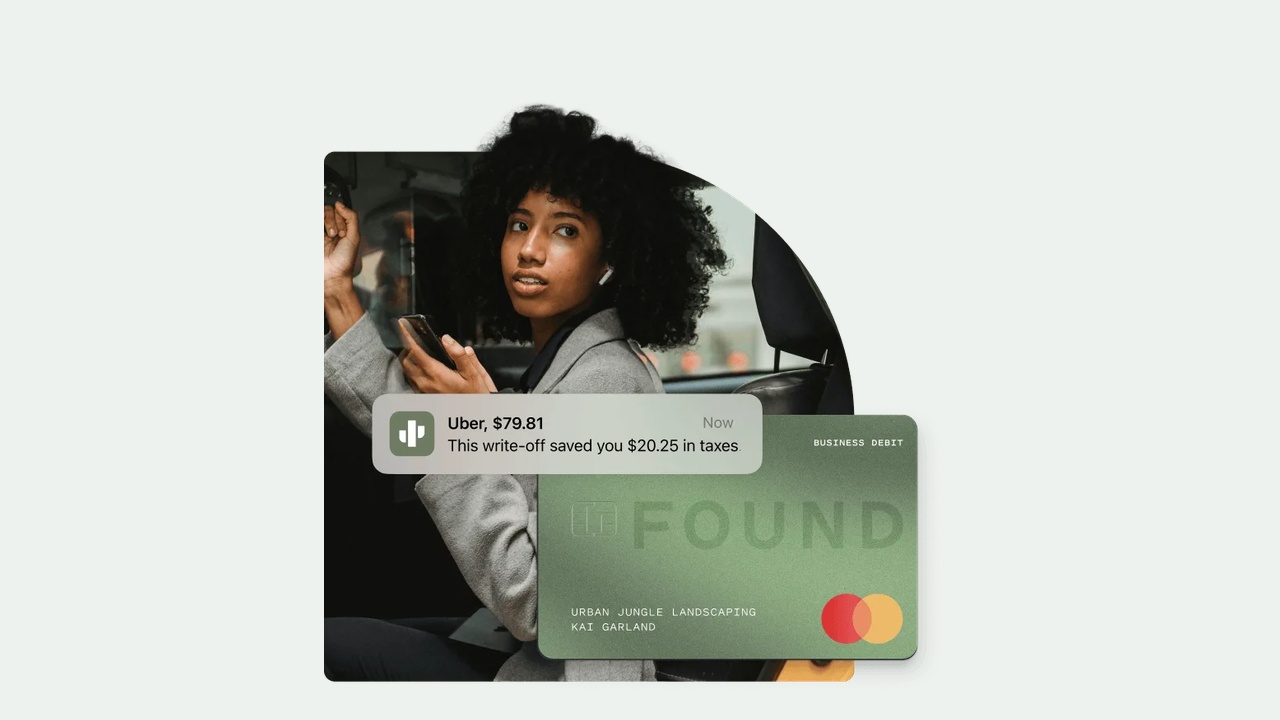
When you operate as an independent contractor, clients pay you gross income without deducting federal, state, or self-employment taxes. Found solves this automatically. Every time client money hits your account, Found’s smart tax algorithm calculates your estimated tax obligation based on your cumulative income and automatically transfers that exact slice into a dedicated "Tax Pocket" that you cannot accidentally spend.
Furthermore, whenever you swipe your Found business debit card, the app instantly prompts you to snap a photo of the receipt, automatically tags the expense to the corresponding IRS Schedule C tax category (such as advertising, business meals, supplies, or home office), and recalculates your estimated tax bill in real time. It even generates and files 1099-NEC forms for subcontractors you pay. For sole proprietors who don’t want to hire a costly bookkeeper or buy separate accounting software, Found is an all-in-one financial operating system.
• Who It Is Best For: Independent contractors, freelancers, and sole proprietors who dread quarterly estimated taxes, struggle with expense categorization, and want their bank account to double as an automated tax preparer.
8. ⚠️ Critical Safety Warning: Why an App Is Not a Bank (The BaaS & Synapse Lesson)
Before opening an account on any digital platform, every freelancer must understand a fundamental financial reality: an app is not a bank.
Four of the five providers on this list (Relay, Bluevine, Mercury, and Found) are financial technology companies (fintechs), not chartered banks. They partner with regulated, FDIC-insured depository institutions (such as Thread Bank, Coastal Community Bank, Choice Financial Group, and Lead Bank) to hold your money. While FDIC insurance protects your funds up to $250,000 (or millions through sweep networks) if the underlying bank goes bankrupt, it does not automatically protect you if the intermediary technology middleware fails.
This risk became painfully real in May 2024 when fintech middleware provider Synapse collapsed into bankruptcy, freezing more than $265 million in customer deposits across 100,000+ accounts for months due to unreconciled internal ledger disputes between partner banks. To safeguard your business cash flow, always follow three golden safety rules:
1. Identify the Real Bank: Always read the bottom of the provider’s homepage to verify the exact FDIC-member chartered bank holding your legal deposits.
2. Never Keep 100% of Operating Cash in One App: Maintain a secondary backup business or personal account at an established brick-and-mortar bank with at least 30 to 60 days of living and business expenses.
3. Regularly Sweep Excess Cash: Keep 1 to 2 months of operational working capital in your fintech account for day-to-day client invoicing, and sweep surplus earnings into a secure high-yield savings account or Treasury bills.
💡 Summary Decision Matrix: Which Account Fits Your Freelance Workflow?
Choosing the right business bank account depends entirely on your business model, client locations, and operational pain points. Here is your quick selection cheat sheet:
• Choose Found (#1) if tax season fills you with dread, you hate manual bookkeeping, and you want automatic tax-withholding pockets on every client dollar.
• Choose Wise Business (#2) if you bill international clients in foreign currencies and want to avoid predatory wire and exchange rate fees.
• Choose Mercury (#3) if you run a digital agency, need free domestic and international USD wires, and want software-grade developer tools.
• Choose Bluevine (#4) if you hold a large cash cushion ($10,000+) and want to earn 1.30% APY directly in your checking account with cash deposit options.
• Choose Relay (#5) if you practice the Profit First budgeting system and need up to 20 sub-accounts to visually divide your business cash flow.
Take the next step in optimizing your independent business finances with Percentio’s free professional planning calculators:
• Freelance Hourly Rate Calculator — Calculate your true billable client rate factoring in taxes, benefits, and expenses.
• Tax Calculator — Accurately estimate your federal and state self-employment tax liabilities.
• Profit Margin Calculator — Analyze gross and net profit margins across your freelance service packages.
• Savings Calculator — Map out your roadmap to a fully funded 6-month business emergency cushion.
• Investment Calculator — Project how investing your surplus freelance profits compounds into long-term personal wealth.
Explore our complete suite of 40+ free wealth-building models at Percentio Financial Calculators.
Keep exploring Percentio
Browse the full directory to find related calculators and compare the assumptions that matter to your situation.
Browse all financial calculators →Related Blogs
Questions and answers
Practical answers to common planning questions.